

Responsible AI in Insurance: Underwriting, Claims and Customer Fairness
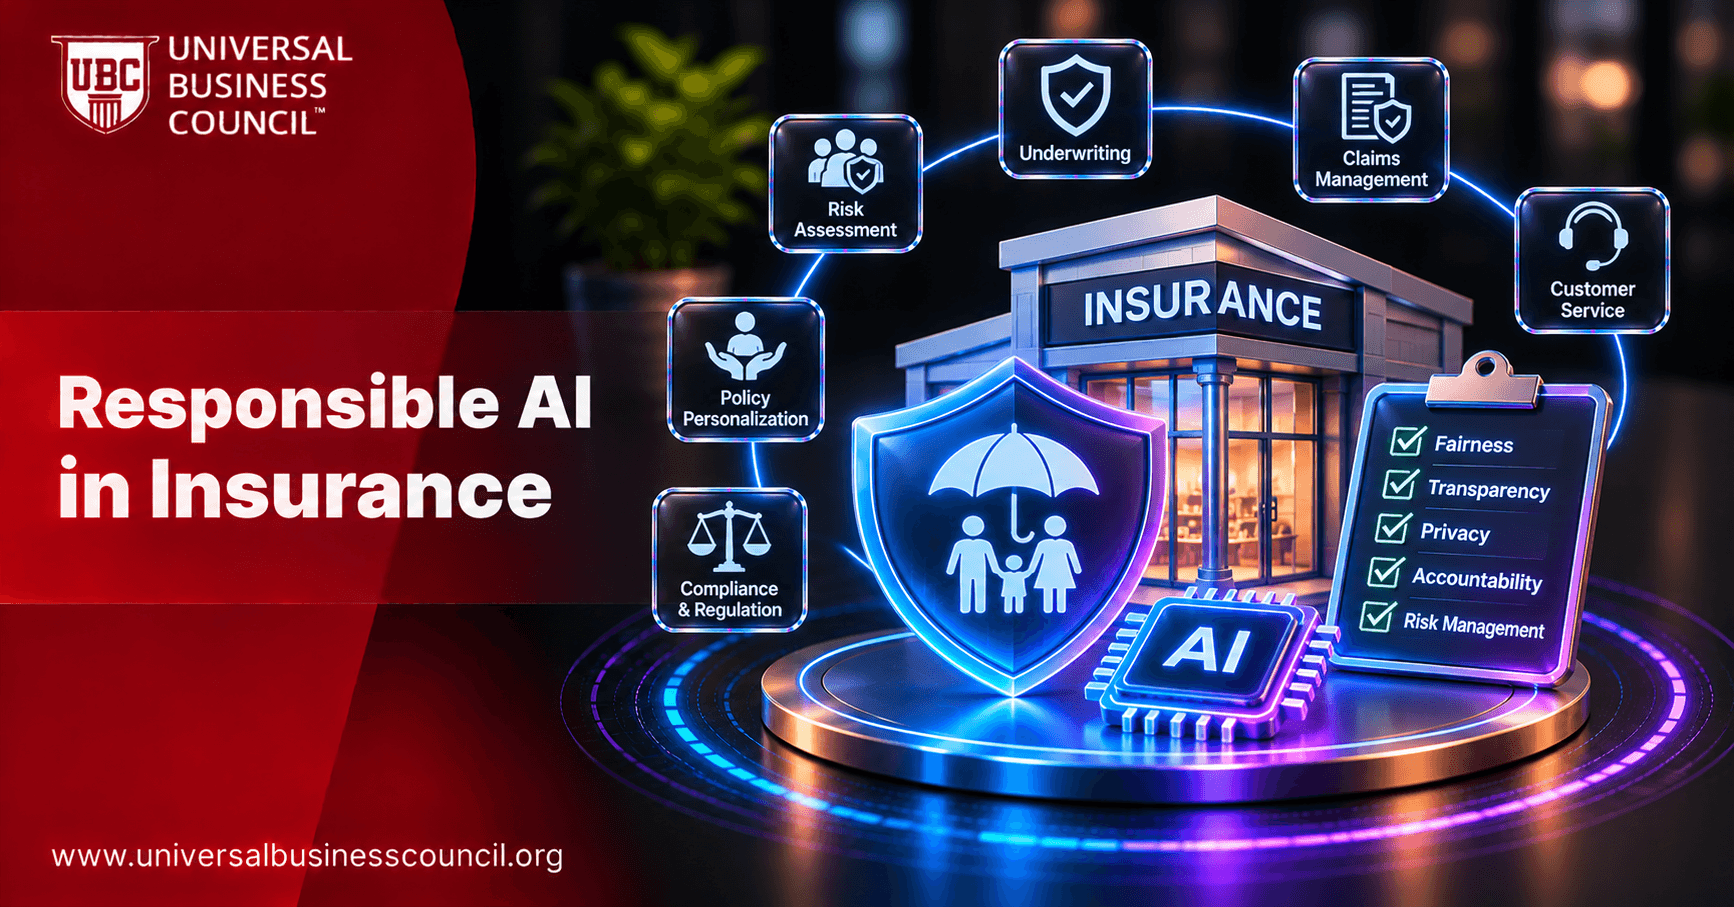
Insurance runs on prediction, which is exactly what AI does well. Models can price risk, flag suspicious claims, speed up payouts and answer customer questions at scale. They can also reproduce unfair patterns, deny valid claims without explanation or use data in ways customers never expected. Because insurance is a regulated, trust-based business that people rely on at difficult moments, responsible AI in insurance has particular weight. This guide covers the main uses, risks and controls across underwriting, claims and customer service, with a focus on fairness. For professional learning in the field, see the certified responsible AI expert certification. This is general information, not legal advice.
What is responsible AI in insurance?
Responsible AI in insurance means using AI in pricing, underwriting, claims, fraud detection, distribution and service in ways that are lawful, fair, transparent, secure and accountable. It builds on existing duties around actuarial soundness, fair treatment of customers, data protection, conduct and model risk management.

Insurers already understand model governance. The task is to extend it to machine learning, new data sources and generative tools.
Underwriting and pricing
Underwriting decisions determine who gets cover and at what price, so fairness and legality are central.
Risk of unfair discrimination
Insurance legitimately distinguishes between risks, but laws in many places restrict the use of certain characteristics and sometimes their proxies. Complex models and new data sources, such as behavioral or third-party data, can introduce proxies that produce indirect discrimination. Review variables, test outcomes across groups and document the justification for each factor used.
Data quality and permission
Check where data comes from, whether it is accurate and whether the customer would reasonably expect its use. Be careful with data from connected devices, social platforms and data brokers, which raise privacy and fairness concerns.
Explainability and customer rights
Customers who are declined, charged more or offered limited cover often have a right to understand why. Choose models and explanation methods that give clear, accurate reasons, and make sure staff can explain outcomes in plain language.
Review rating factors for proxies and legal limits
Test outcomes across relevant groups
Verify data sources, accuracy and permission
Provide clear reasons for adverse decisions
Claims handling
Claims are where customers most need the insurer to act fairly.
Automation and speed
AI can triage claims, assess damage from images and speed up straightforward payouts. Faster resolution benefits customers, provided that accuracy is high and errors are caught.
Fraud detection
Fraud models protect the pool of policyholders, but false positives can delay or deny legitimate claims and may affect some groups more than others. Treat a fraud flag as a reason for review, not as a conclusion. Keep a human in the loop for adverse decisions, and give customers a way to respond and appeal.
Consistency and fairness
Monitor settlement outcomes, delays and denial rates across customer groups and regions. Unexplained gaps deserve investigation.
Vulnerable customers
Customers may be distressed, ill or in financial difficulty when they claim. Design processes that detect signs of vulnerability and route those customers to trained staff.
Customer service and distribution
Chatbots and recommendation tools shape how customers understand and buy products.
Honest advice and disclosure
Make sure automated tools do not mislead customers about cover, exclusions or prices, and that they hand over to humans when needed. Disclose when customers are dealing with AI. Marketing teams should keep claims accurate, and a digital marketing course can help them communicate product benefits without overstating them.
Personalization limits
Personalized offers and pricing can be useful, but they should not exploit customers' vulnerabilities or inertia. Review practices against conduct and consumer protection rules.
Model risk, governance and security
Strong governance underpins all of this.
Validate and monitor
Independent validation, a model inventory, performance and drift monitoring and clear approval gates should apply to AI models just as to traditional ones. Re-test after changes in data, portfolio or economic conditions. Technical teams that build and monitor these models benefit from solid foundations, which many develop through tech certifications.
Manage vendors and data partners
Insurers rely on third-party models, data and platforms. Perform due diligence, contract for transparency, audit and incident reporting and understand dependencies.
Protect data and systems
Insurance data is detailed and sensitive. Apply strong access control, encryption and security testing, including AI-specific threats such as data extraction and prompt injection.
Keep reliable records
Maintain evidence of model development, validation, approvals, monitoring and customer outcomes in tamper-evident form, an area linked to topics in deep tech certifications.
Verify people
Staff and contractors with access to models, claims data or approval authority should be qualified and properly vetted. Services such as HireValid support credential and background verification.
Conclusion
Responsible AI in insurance means fair, explainable and well-governed use of AI across underwriting, claims and customer service. Review rating factors and data for discrimination and proxies, keep humans involved in adverse claims decisions, protect vulnerable customers and communicate honestly. Apply model risk management, vendor oversight, security, reliable records and verified people. Regulators and customers will judge insurers on outcomes, so monitor those outcomes continuously.
Frequently asked questions
These are the questions insurers ask most about AI.
1. How is AI used in insurance?
In pricing, underwriting, claims, fraud detection and customer service.
2. What is the main fairness risk?
Unfair discrimination, including through proxy variables.
3. What is a proxy variable?
A factor that indirectly reflects a protected characteristic.
4. Can insurers use any data?
No. Law, ethics and customer expectations limit data use.
5. Do customers have a right to reasons?
Often yes for adverse decisions, depending on local law.
6. Can AI deny a claim on its own?
Adverse decisions should involve human review and an appeal route.
7. How should fraud models be used?
As a trigger for review, not as a final verdict.
8. What are false positives in fraud detection?
Legitimate claims wrongly flagged as suspicious.
9. How do we monitor claims fairness?
Track outcomes, delays and denials across groups and regions.
10. Who counts as a vulnerable customer?
Those whose circumstances make them more exposed to harm, such as illness or financial difficulty.
11. Can chatbots sell insurance?
Yes, with accurate information, disclosure and human handover.
12. Is personalized pricing allowed?
Within legal limits, and it should not exploit vulnerabilities.
13. What validation is needed?
Independent review of data, performance, stability and limitations.
14. How do we handle third-party models?
Run due diligence and require transparency, audit rights and incident notice.
15. What security risks apply?
Data extraction, poisoning, prompt injection and misuse.
16. What records should we keep?
Development, validation, approvals, monitoring and customer outcomes.
17. How often should models be reviewed?
On a risk-based schedule and after major changes.
18. Does generative AI change the picture?
It adds risks of inaccurate advice, so add controls and review.
19. Who is accountable for AI decisions?
The insurer, through named owners and governance.
20. Where do we get legal certainty?
From qualified advisers who know insurance regulation in each market.
Related Articles
View All
Artificial Intelligence
Responsible AI KPIs: How to Measure Fairness, Transparency and Trust
Learn how to measure responsible AI performance using key performance indicators (KPIs). Explore the metrics organizations can use to track AI fairness, transparency, accountability, privacy, safety, and compliance while evaluating AI systems and strengthening responsible AI practices.
Artificial Intelligence
Responsible AI in Customer Service: Safe and Trustworthy AI Chatbots
Explore how responsible AI can make customer service more reliable, secure, and trustworthy. Learn how businesses can build safer AI chatbots by protecting customer data, reducing biased responses, improving transparency, and maintaining human oversight.
Artificial Intelligence
Responsible AI in Education: Student Privacy, Fairness and AI-Powered Learning
Explore how responsible AI is shaping education through personalized learning, smarter teaching tools, and more accessible educational experiences. Learn how schools can protect student privacy, reduce algorithmic bias, promote fairness, and maintain human oversight in AI-powered learning.
Trending Articles
The Role of Blockchain in Ethical AI Development
How blockchain technology is being used to promote transparency and accountability in artificial intelligence systems.
AWS Career Roadmap
A step-by-step guide to building a successful career in Amazon Web Services cloud computing.
Top 5 DeFi Platforms
Explore the leading decentralized finance platforms and what makes each one unique in the evolving DeFi landscape.